Patel Pratik & Co. | CA, CPA

IFRS vs US GAAP: Key Differences That Matter to International Businesses

A business can spend the same money, develop the same product and sign the same lease—and report different results under IFRS and US GAAP.

Those differences matter when a founder presents accounts to investors, a group consolidates an overseas subsidiary or a lender assesses financial performance.

The useful question is which accounting differences could change the decisions people make about your business. Four areas deserve particular attention: development costs, inventory, leases and impairment.

First, establish which reporting framework you need

IFRS Accounting Standards are issued by the International Accounting Standards Board. US GAAP for nongovernmental entities is principally contained in the FASB Accounting Standards Codification.

Your reporting basis depends on the applicable requirements and the purpose of the accounts. Local statutory reporting, group consolidation and investor reporting may require different information.

Do not assume that approaching US investors automatically requires a complete US GAAP conversion. The SEC’s Financial Reporting manual explains that qualifying foreign private issuers can file financial statements complying with IFRS as issued by the IASB without reconciling them to US GAAP. The relevant compliance statements and audit opinion matter.

Confirm the actual requirement before commissioning conversion work. This article compares full IFRS with US GAAP; it does not cover every local adaptation, private-company alternative or industry-specific rule.

1. Development costs: when spending becomes an asset

Under IAS 38, research expenditure is expensed. Development expenditure must be capitalised when the specified recognition conditions are met. Capitalisation records qualifying expenditure as an asset rather than immediately charging it all against profit.

The distinction requires evidence. Calling a project “development” in a budget does not establish that it qualifies. Document the relevant conditions, the date they were first satisfied and the costs incurred afterwards.

Under US GAAP, costs within ASC 730’s research-and-development scope are generally expensed as incurred. However, software and certain acquired assets have separate requirements. “US GAAP expenses every development cost” is an unsafe shortcut.

Software businesses should check the applicable guidance and adoption status. FASB’s issued ASU 2025-06 changes internal-use software accounting for annual periods beginning after 15 December 2027, with early adoption permitted. It should not automatically be treated as mandatory for 2026 accounts.

Worked example: the same project, different reported profit

Assume a fictional manufacturer develops a non-software product during 2026. Research expenditure is incurred before development begins. All subsequent development expenditure meets IAS 38’s conditions when incurred, while the expenditure falls within ASC 730 under US GAAP.

The asset becomes available for use on 1 October 2026. Its useful life is three years, with straight-line amortisation and no residual value or impairment.

Figures are whole US dollars. All project costs are paid during 2026. Tax effects, financing and other accounting differences are excluded; this is not a country-specific tax computation.

ItemCalculation or basisUSD
Research expenditureAssumed project cost60,000
Qualifying development expenditureAssumed project cost180,000
Total project cash payments60,000 + 180,000240,000
Annual IFRS amortisation180,000 ÷ 3 years60,000
IFRS amortisation for 202660,000 × 3/1215,000
IFRS asset at year-end180,000 − 15,000165,000

Amortisation spreads the asset’s cost over its useful life. Here, it begins when the asset is available for use.

Reporting itemIFRS: USDUS GAAP: USD
Profit before project costs and tax400,000400,000
Research expense(60,000)(60,000)
Development expenditure expensed immediately—(180,000)
Development asset amortisation(15,000)—
Profit before tax325,000160,000
Development asset at year-end165,0000
Total project cash payments240,000240,000

The IFRS result includes a recognised asset and a smaller current-period expense. The project has not generated extra cash because of that accounting treatment.

For an investor comparison, explain the adjustment and the future amortisation attached to the asset. Comparing profit figures without that context can give a misleading impression of performance.

2. Inventory: the cost formula can change margins

IAS 2 permits FIFO or weighted-average costing for ordinarily interchangeable inventory and requires specific identification for appropriate non-interchangeable items. LIFO—last in, first out—is not permitted under IFRS. US GAAP permits LIFO.

FIFO assigns the earlier purchase costs to goods sold; LIFO assigns the later costs first. When purchase prices rise, those choices can produce different inventory values and gross margins.

An IFRS reporting group acquiring a US business using LIFO should assess the conversion adjustment before comparing operating results.

Also check subsequent measurement. IFRS generally uses the lower of cost and net realisable value. Under US GAAP, inventory using LIFO or the retail inventory method retains a different lower-of-cost-or-market model.

Ask for inventory policies, cost layers and valuation workings. A closing stock figure alone may not explain the difference.

3. Leases: balance-sheet recognition does not make the models identical

Both frameworks generally bring lessee lease assets and liabilities onto the balance sheet, subject to relevant exceptions.

IFRS 16 generally uses a single lessee model, with depreciation of the right-of-use asset and interest on the lease liability. US GAAP’s ASC 842 retains finance and operating lease classifications. An operating lease generally produces a single straight-line lease expense; a finance lease separates amortisation and interest.

For a lease treated as operating under US GAAP, IFRS reporting can therefore show a different expense pattern and different components within performance measures.

That can affect EBITDA comparisons, depending on the definition used. Review the lease schedules and the metric’s calculation together. Neither the accounting label nor a higher EBITDA figure changes the contractual rent payable.

4. Impairment: a recovery may be treated differently

For assets within IAS 36, IFRS compares carrying value with recoverable amount. Where the relevant conditions are met, an impairment loss on an asset other than goodwill is reversed, subject to a ceiling based on the carrying amount without the earlier impairment. Goodwill impairment is never reversed.

Under US GAAP, previously recognised impairment losses on long-lived assets held and used under ASC 360 cannot be reversed. This comparison should not be extended indiscriminately to inventory, financial instruments or assets held for sale, which have different guidance.

When reviewing a recovering business, examine its impairment history. An improvement in trading conditions may affect the two sets of accounts differently.

Build a reconciliation that supports decisions

For cross-border reporting, I would start with five checks:

  1. Confirm the reporting purpose. Establish what each regulator, parent company, lender or investor actually requires.
  2. Identify material differences. Prioritise the transactions capable of changing reported profit, assets or agreed financial measures.
  3. Collect supporting records. Retain project approvals, cost records, inventory layers, lease schedules and impairment workings.
  4. Separate recurring adjustments. Maintain opening balances, current-period movements and future expense effects for each material difference.
  5. Explain the commercial meaning. Show which changes reflect accounting requirements and which reflect changes in the business itself.

A useful IFRS-to-US-GAAP reconciliation connects each material adjustment to evidence and explains its effect over time. Start there before using reported margins or asset values to judge performance, agree lending terms or negotiate a transaction.

Patel Pratik & Co. can support businesses with financial-reporting reviews, cross-border reporting analysis and the assessment of material accounting differences.
IFRS 18: Why 2026 Is the Year to Rethink Your Profit & Loss Reporting

Two businesses can report identical profit before tax, yet present very different pictures of operating performance. IFRS 18 is designed to improve how financial performance is presented and compared.

For finance teams, the immediate task is understanding how existing reporting will translate into the new structure. For calendar-year businesses first applying IFRS 18 in 2027, that includes preparing 2026 comparative information.

The starting point is a question: can your current records explain every change between your existing profit and loss statement and the IFRS 18 version?

Why IFRS 18 matters in 2026

IFRS 18, Presentation and Disclosure in Financial Statements, replaces IAS 1. It applies to annual reporting periods beginning on or after 1 January 2027, with earlier application permitted. Check relevant local endorsement or adoption requirements alongside it.

Application is retrospective: comparative information must reflect the new requirements. A company first applying IFRS 18 for the year ending 31 December 2027 will therefore restate its 2026 comparatives. Companies with different year-ends must identify their own transition periods. First-year interim reporting also needs attention.

Annual transition disclosures include a reconciliation, for each profit and loss line item, between the immediately preceding comparative period’s restated figures and those previously presented under IAS 1.

Waiting until the 2027 year-end could leave the team reconstructing information that its systems never captured separately.

What changes in the income statement?

IFRS 18 requires income and expenses in the statement of profit or loss to be classified into five categories:

CategoryWhat it covers
OperatingIncome and expenses not classified in the other four categories.
InvestingSpecified returns and related income or expenses from investments, cash and other assets generating returns largely independently.
FinancingSpecified income and expenses from financing liabilities, plus interest-related items from certain other liabilities.
Income taxesTax expense or income within IAS 12 and related foreign exchange differences.
Discontinued operationsIncome and expenses classified under IFRS 5.

The standard also introduces two defined subtotals: operating profit or loss and profit or loss before financing and income taxes. The second combines the operating and investing categories.

Classification depends on the business. Special rules apply where investing in assets or financing customers is a main business activity. Certain financing businesses also have an exception to presenting the second subtotal. A manufacturer’s mapping cannot simply be copied into a bank’s accounts.

Operating profit can include unusual or volatile operating expenses. It should not be treated as a measure of recurring earnings.

Worked example: different operating profit, unchanged total profit

Consider a fictional standalone manufacturer. Investing and customer financing are not its main business activities. Both columns use identical 2026 transactions; only presentation changes.

Amounts are whole US dollars. The example assumes a 25% illustrative income tax rate, with no tax differences or discontinued operations. This is a simplified presentation example, not a country-specific tax computation.

Line itemPrevious IAS 1 presentation: USDIFRS 18 presentation: USD
Revenue1,000,0001,000,000
Cost of sales(600,000)(600,000)
Gross profit400,000400,000
Administrative expenses(180,000)(180,000)
Restructuring expense(20,000)(20,000)
Deposit interest included above operating profit10,000—
Operating profit210,000200,000
Deposit interest: investing category—10,000
Profit before financing and income taxesNot presented210,000
Borrowing interest: financing expense(30,000)(30,000)
Profit before tax180,000180,000
Income tax: 180,000 × 25%(45,000)(45,000)
Profit for the year135,000135,000

The previous column illustrates this company’s assumed presentation; IAS 1 did not prescribe that treatment for every business.

Under IFRS 18, its deposit interest sits in investing. The restructuring cost remains operating.

The lower operating subtotal does not indicate weaker trading in this comparison. Finance teams should explain the reclassification before stakeholders interpret it as a performance decline.

What are management-defined performance measures?

A management-defined performance measure, or MPM, is a qualifying income-and-expense subtotal used in public communications outside the financial statements to communicate management’s view of the entity’s overall financial performance. Measures listed in IFRS 18 or specifically required by another IFRS Accounting Standard are excluded. An internal KPI does not automatically qualify.

Assume the manufacturer publicly reports adjusted operating profit excluding restructuring costs. The following illustrates its reconciliation. The restructuring expense is assumed fully tax-deductible at the illustrative rate; there are no non-controlling interests.

Measure or disclosureCalculation or basisUSD
IFRS 18 operating profitAs presented above200,000
Add back restructuring expenseExpense included in operating profit20,000
Adjusted operating profit200,000 + 20,000220,000
Tax benefit associated with the excluded expense20,000 × 25%5,000
Non-controlling interest effectStandalone entity0

The tax-benefit row is a separate disclosure; it is not added to adjusted operating profit.

Required MPM information belongs in a single note. It includes the calculation, why management considers the measure useful, reconciliation to the most directly comparable qualifying IFRS total or subtotal, and each reconciling item’s tax and non-controlling-interest effects. Changes to the measure also require explanation.

Adding back restructuring costs in an adjusted measure does not remove them from IFRS operating profit. The reconciliation illustrates that distinction; it is not a complete disclosure note.

What CFOs and finance teams should review

Start with chart-of-accounts mapping and consolidation packages. A single interest or foreign-exchange account may contain transactions needing different treatment. Document the underlying transactions and classification judgements.

Review management dashboards, investor materials, lending agreements and incentive arrangements that refer to operating profit. Determine whether their definitions require clarification; a reporting change does not automatically rewrite a contract.

Aggregation and disaggregation also matter: group items with shared characteristics and separate information where material differences would otherwise be obscured. Review broad “other expenses” labels.

The specified expense-by-nature disclosure requirements apply when any operating-category expense line is classified by function. This can require additional reporting data.

Include cash-flow reporting in the project: consequential IAS 7 amendments require operating profit as the starting point for the indirect method.

Five preparation steps before 2027

  1. Confirm the timetable. Identify the first annual reporting period, comparative periods, relevant interim reports and local requirements.
  2. Document classification decisions. Assess main business activities and map material income and expenses, with supporting reasons.
  3. Test comparative data. Produce a draft restated profit and loss statement and retain the reconciliation to previously reported figures.
  4. Establish disclosure controls. Identify qualifying MPMs, assign owners and collect adjustment, tax and supporting expense data.
  5. Run a complete reporting rehearsal. Review draft statements, notes and system outputs with relevant stakeholders and auditors where applicable.

IFRS 18 requires businesses to reconsider how performance is classified, explained and communicated. A useful next step is to prepare one draft IFRS 18 statement using your own comparative data. The gaps it exposes will make the implementation work clearer.

Patel Pratik & Co. can support finance teams with reporting reviews, classification analysis and practical transition planning.

Taxation & Compliance for Foreign Investors in India

India has emerged as a major investment destination due to its large consumer market and growing economy. However, foreign companies and individuals investing in India must navigate a complex taxation and regulatory framework. This guide provides an in-depth overview of the taxation and compliance requirements for foreign investors in India.

Modes of Foreign Investment in India

Foreign investors can enter India in various ways, including:

Foreign Direct Investment (FDI)

Investment in an Indian company through equity shares, convertible instruments, or preference shares.

Foreign Portfolio Investment (FPI)

Investment in securities such as listed shares, bonds, and mutual funds.

External Commercial Borrowings (ECBs)

Loans raised by Indian entities from foreign sources.

Investment in Real Estate & Infrastructure

Allowed under specific conditions.

Joint Ventures & Wholly-Owned Subsidiaries

Setting up an Indian company under the Companies Act, 2013.

Key Taxation Aspects for Foreign Investors

Foreign investors must comply with the Indian Income Tax Act, 1961, as well as Goods and Services Tax (GST) and other regulatory requirements. The major tax aspects include:

Corporate Taxation for Foreign Companies

Tax Rates

Foreign companies are taxed at 40% (plus surcharge and cess) on income earned in India.

Permanent Establishment (PE)

If a foreign company has a business connection in India (e.g., branch, project office, or agent), it may be subject to corporate tax in India.

Transfer Pricing Regulations

Transactions between related entities must comply with Indian transfer pricing rules under Sections 92-92F of the Income Tax Act.

Withholding Tax (TDS)

Payments made to foreign companies for services, royalties, dividends, or interest are subject to withholding tax (varies based on Double Taxation Avoidance Agreements – DTAA).

Minimum Alternate Tax (MAT)

If a foreign company has a PE in India, MAT at 15% (plus surcharge and cess) may apply.

Taxation for Foreign Individuals Investing in India

Capital Gains Tax

Short-term capital gains (STCG) on listed shares (less than 12 months) – 15%

Long-term capital gains (LTCG) on listed shares (more than 12 months) – 10% (above ₹1 lakh)

STCG on unlisted securities – As per slab rates

LTCG on unlisted securities – 10% without indexation

Dividend Income

Taxed at 20% for foreign investors, subject to DTAA benefits.

Rental Income

Taxable at slab rates for individuals or corporate tax rates for companies.

Interest Income

Typically taxed at 5-20%, depending on the nature of the investment and DTAA provisions.

GST Compliance

Import of services is subject to reverse charge mechanism (RCM) where the Indian recipient pays GST.

Businesses involved in e-commerce or digital services may fall under India’s Equalization Levy (6% on specified services).

Regulatory Compliance for Foreign Investors

Foreign investors must comply with the Foreign Exchange Management Act (FEMA) and Reserve Bank of India (RBI) guidelines. Key requirements include:

Filing Forms & Returns

Filing with RBI & FEMA

FC-GPR

Required when a foreign investor subscribes to shares in an Indian company.

FC-TRS

Required when a foreign investor transfers shares to/from an Indian resident.

Annual FLA Return

Mandatory for entities receiving foreign direct investments.

Income Tax Filings

Form ITR-3 or ITR-5 (for individuals/partnerships with business income in India).

Form ITR-6 (for foreign companies operating in India).

Tax Deducted at Source (TDS) Returns if applicable.

GST Returns (if applicable)

GSTR-1, GSTR-3B (for companies providing taxable supplies in India).

Transfer Pricing Documentation

Foreign entities engaged in inter-company transactions must maintain documentation under Rule 10D and file Form 3CEB.

DTAA & Tax Exemptions

Investors from countries with DTAA agreements with India can claim reduced tax rates on dividends, royalties, and capital gains.

Special Considerations for Startups & Venture Capital Investments

Foreign investors in startups (eligible under Startup India) can benefit from reduced LTCG tax rates.

Angel Tax exemption is available for investments made by foreign entities in registered startups.

Venture capital investments may be eligible for tax pass-through treatment under Section 10(23FB).

Penalties & Non-Compliance Risks

Failure to comply with taxation and regulatory norms can lead to severe penalties, including:

Interest and penalties under Income Tax Act (e.g., 1% per month for late filing of tax returns).

Non-filing of FC-GPR, FC-TRS, or FLA Return can attract hefty fines from RBI.

Transfer pricing violations can lead to adjustments and penalties up to 100% of tax underpaid.

GST non-compliance can result in penalties up to 100% of tax due.

Conclusion

Foreign investors in India must carefully navigate the taxation and compliance landscape to ensure smooth operations and avoid legal issues. Engaging a tax advisor or compliance expert can help in structuring investments optimally and ensuring full regulatory compliance. The key is to stay updated with changing tax laws, take advantage of DTAA benefits, and adhere to mandatory filing requirements to avoid penalties.

By following the above guidelines, foreign investors can efficiently manage their tax obligations and maximize their returns in India.

Case Study: Uncovering Financial Mismanagement in a Cooperative Society

Introduction: A Case That Needed Answers

In 2010, a cooperative society faced allegations of financial mismanagement and fraud. At the center of the controversy was the repair of an overhead water tank—a seemingly routine maintenance task that revealed systemic irregularities. As a forensic accountant, I was brought in to unravel the truth. This case is a testament to how forensic accounting can expose the layers of deceit hidden in plain sight.

This case study takes you through the investigation, the challenges faced, and the lessons learned.

The First Signs of Trouble: A Routine AGM Raises Questions

The story begins in July 2010, during the Annual General Meeting (AGM) of the cooperative society. The meeting resolved to repair the overhead water tank, but the minutes lacked critical details about costs, contractor selection, and tendering processes—a red flag for transparency. By August 2010, concerns began to mount among society members.

Key Issues Identified

Lack of transparency in meeting minutes.

Missing details about contractor selection.

Bylaw violations concerning financial disclosures.

    Unveiling the Web: Suspicious Contractor Quotations

    In October 2010, two contractor quotations emerged, both dated the same day and originating from companies sharing the same address. This raised immediate suspicions about the legitimacy of these firms.

    Observations

    • The absence of detailed cost breakdowns.
    • A shared address for two supposedly independent contractors.

    Approval and Payment: The Plot Thickens

    By November 2010, the society’s Working Committee approved repairs for ₹1,30,000 without consulting members. Payments were issued via bearer cheques—a method bypassing transparency norms and society bylaws.

    Investigative Findings

    • Cheques totaling ₹81,100 were signed by key committee members but withdrawn by an unaffiliated individual.
    • Signature discrepancies on cheque endorsements indicated forgery.

    The Forensic Approach: Connecting the Dots

    As a forensic accountant, my role was to sift through documents, identify anomalies, and connect the seemingly unrelated dots. Each piece of evidence pointed toward deliberate financial mismanagement.

    Techniques Employed

    Document Analysis

    Reviewed AGM minutes, contractor quotations, and payment records.

    Signature Verification

    Conducted forensic handwriting analysis, revealing forgery.

    Transaction Tracing

    Followed the money trail to identify unauthorized withdrawals.

      False Narratives: Misrepresentation to Members

      Circulars issued in December 2013 claimed payments were made via cheques, contradicting the actual bearer cheque transactions. The committee’s deliberate misrepresentation further complicated the accountability trail.

      Evidence Highlights

      • Circular discrepancies exposing false claims.
      • Meeting minutes misrepresenting key facts.

      Legal and Regulatory Breaches

      This case wasn’t just about mismanagement; it also highlighted violations of multiple laws

      Society Bylaws

      Transactions above ₹1,500 were required to be made via cross-cheques.

      Indian Contract Act

      The absence of contractor legitimacy undermined the contract’s validity.

      Prevention of Money Laundering Act (PMLA)

      Issuing bearer cheques to fictitious entities suggested attempts to disguise financial misconduct.

      Negotiable Instruments Act

      Forged endorsements invalidated the cheques under Section 87.

      Resolution: Bringing Accountability

      After presenting a detailed report, including forensic evidence and legal violations, the findings were submitted to the appropriate authorities. The implicated committee members were held accountable for their actions, ensuring justice and transparency for the society.

      Lessons Learned: Red Flags to Watch For

      This case underscores the importance of vigilance in financial transactions. Here are key takeaways

      Transparency in Decision-Making

      Always document and disclose critical decisions.

      Due Diligence

      Verify the legitimacy of contractors and transactions.

      Adherence to Bylaws

      Financial governance rules exist for a reason.

      Forensic Investigation

      The power of detailed analysis can unravel even the most complex frauds.

          Conclusion: The Power of Forensic Accounting

          This case serves as a reminder that financial integrity is non-negotiable. As forensic accountants, we play a crucial role in safeguarding organizations from fraud and ensuring accountability. While the journey was challenging, the resolution brought peace of mind to the society members and reaffirmed the importance of transparency.

          This is one of many stories where forensic accounting serves justice and restores trust. Stay vigilant, and remember—the numbers never lie, but they do require interpretation.

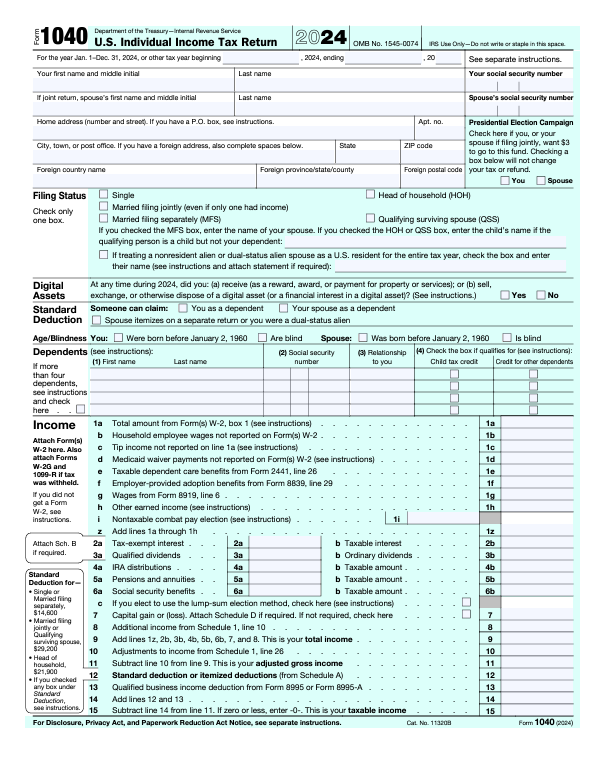
          Mastering the 2024 Form 1040: A Guide to Filing Your U.S. Individual Income Tax Return

          Tax season is often accompanied by anxiety, confusion, and the endless quest for accurate information. For most U.S. taxpayers, Form 1040 is at the heart of this process. Whether you’re a seasoned filer or preparing your taxes for the first time, understanding this essential document is key to maximizing your refund or minimizing your liability.

          In this guide, we’ll walk through Form 1040 for the 2024 tax year, breaking it down step by step and highlighting key changes and nuances that could impact your filing.

          What Is Form 1040?

          Form 1040, officially known as the U.S. Individual Income Tax Return, is used by taxpayers to report their annual income to the IRS. It captures various details, including income, deductions, credits, and tax liabilities. Depending on your financial situation, you may also need to attach additional schedules or forms.

          What’s New in 2024?

          Digital Assets Reporting

          The 2024 Form 1040 includes a section dedicated to digital assets. Taxpayers must disclose if they received, sold, exchanged, or disposed of digital assets such as cryptocurrency. This addition reflects the IRS’s increasing focus on crypto transactions.

          Standard Deduction Increase

          • Single or Married Filing Separately: $14,600
          • Married Filing Jointly or Qualifying Surviving Spouse: $29,200
          • Head of Household: $21,900
            These increases are designed to adjust for inflation and benefit taxpayers who opt not to itemize deductions.

          Enhanced Child Tax Credit

          Schedule 8812 continues to play a significant role in claiming the Child Tax Credit, which can substantially reduce your tax liability.

            Breaking Down the 2024 Form 1040

            Filing Status

            Choosing the correct filing status is critical as it impacts your tax bracket and deductions. Options include:

            • Single
            • Married Filing Jointly
            • Married Filing Separately
            • Head of Household
            • Qualifying Surviving Spouse

            Ensure accuracy, especially if your marital or household situation changed during the year.

            Income

            This section consolidates your earnings from multiple sources. Some key inclusions:

            • Wages from Form W-2
            • Interest income (taxable and non-taxable)
            • Dividends
            • Social Security benefits
            • Capital gains or losses
              Be sure to cross-reference with your Forms W-2, 1099, and other income statements to avoid omissions.

            Adjusted Gross Income (AGI)

            Your AGI is your total income minus eligible adjustments, such as contributions to a traditional IRA, student loan interest deductions, and HSA contributions. This figure is a pivotal determinant of your tax liability and eligibility for certain credits.

            Tax and Credits

            Lines 16–22 summarize your tax liability, factoring in deductions and credits like the Child Tax Credit or American Opportunity Credit. These can significantly reduce what you owe.

            Payments and Refunds

            This section reconciles taxes withheld throughout the year against your liability. Overpayments result in a refund, while underpayments may lead to a balance due. Opting for direct deposit expedites refunds.

            Common Mistakes to Avoid

            Ignoring Digital Asset Disclosures

            Even minor crypto transactions must be reported to avoid penalties.

            Mismatched Information

            Ensure names, Social Security numbers, and other personal details match official records.

            Overlooking Deductions or Credits

            Many taxpayers miss out on deductions or credits due to lack of awareness. Always review Schedule 1 and related forms.

            Missing Deadlines

            The filing deadline for the 2024 tax year is April 15, 2025. Filing late without an extension can result in penalties.

              Tips for a Smooth Filing Experience

              Stay Organized

              Keep all relevant documents, including W-2s, 1099s, and receipts for deductible expenses, in one place.

              Leverage Software or Professional Help

              Tax software simplifies calculations and reduces errors. Complex situations, like owning a business or dealing with international taxes, may warrant hiring a CPA.

              Double-Check Before Filing

              Ensure all forms are complete and accurate. A minor oversight can delay refunds or trigger audits.

                Conclusion

                The 2024 Form 1040 may seem daunting at first glance, but breaking it into manageable sections can make filing far less intimidating. Staying informed about updates, such as the digital asset requirement and standard deduction adjustments, ensures you file accurately and optimize your financial outcomes.

                Whether you’re filing solo or with professional assistance, use this guide as a roadmap to navigate tax season confidently. By mastering your Form 1040, you take a crucial step toward financial empowerment.